


Guri City Provides Concentrated Guidance on Changes to Housing Acquisition Tax Following Regulation Zone Designation
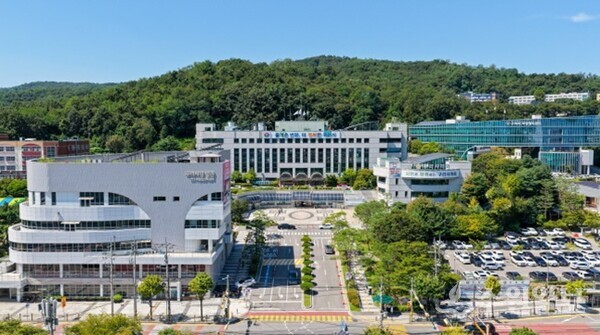
[Suwon Ilbo=Reporter Eom In-yong] Guri City announced on the 2nd that it has begun active guidance to residents regarding the housing acquisition tax system changes effective from the 1st following the Ministry of Land, Infrastructure and Transport's designation of regulation zones (adjustment target areas and speculative overheating zones), and has launched promotional efforts to prevent confusion and disadvantages caused by the tax system changes.
This guidance has been prepared to help residents easily understand the acquisition tax rates and transitional measures that change with the regulation zone designation, and to prevent disadvantages in the housing acquisition process.
With this regulation zone designation, the acquisition tax rates increase when multi-property owners, excluding temporary 2-property owners, and corporations acquire housing in Guri City.
In the existing non-regulation areas, a tax rate of 1-3% for 2-property owners and 8% for 3-property owners was applied, but in regulation zones, a heavy tax rate of 8% for 2-property owners and 12% for 3 or more properties and corporations is applied.
Additionally, when acquiring housing through gift (excluding single-property owners per household), a heavy tax rate of 12% is imposed on housing with a publicly announced price of 300 million won or more within adjustment target areas.
However, transitional measures for taxpayer protection are also implemented together.
When a housing sales contract is concluded and a contract deposit is paid before July 1, 2026—the regulation zone designation date—and the fact is confirmed through supporting documents such as real estate transaction reports, contracts, and financial transaction records, the pre-existing non-regulation area tax rate can be applied even if the balance is paid after the designation date.
Furthermore, if acquisition tax reductions such as those for temporary 2-property owners have been applied, post-management requirements such as housing disposal deadlines must be met, and failure to comply may result in recovery of the reduced tax amount, requiring special attention.
Kim Dae-beom, head of the City Tax Administration Division, stated, "As the acquisition tax burden for multi-property owners and corporations changes with the regulation zone designation, residents planning to acquire housing are urged to verify the contract date, balance payment date, and applicable tax rates." He added, "Even if you qualify for acquisition tax reductions, carefully examine the post-management requirements to avoid administrative and financial disadvantages."
Loading comments…